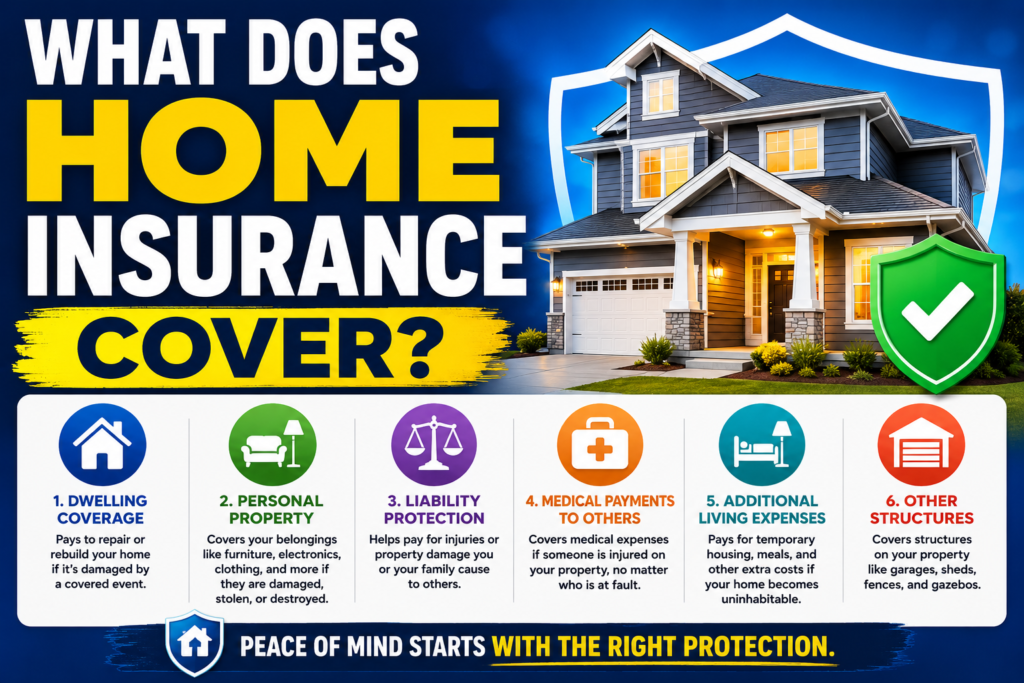
You just closed on a house. The lender required an insurance binder, so you bought the cheapest policy available. You assume you are fully protected. You are not. When disaster strikes, the most dangerous question a homeowner can ask is, what does home insurance cover?
If you wait until your basement is under three feet of water to read your policy, you will likely face financial ruin. Standard homeowners insurance is a highly specific legal contract filled with strict coverage limits, named perils, and unforgiving exclusions. It is not a home warranty. It is not a maintenance plan. This master guide strips away the marketing jargon and exposes exactly how a standard HO-3 policy protects your assets, what it explicitly denies, and how to close the hidden gaps in your coverage.
The “Market Value vs. Rebuild Cost” Trap
Before analyzing what a policy covers, you must understand how it values your home. The biggest mistake first-time buyers make is insuring their home for its real estate market value.
Market value includes the land your house sits on, the neighborhood school district, and local real estate demand. Insurance companies do not care about any of that. A fire does not burn the dirt.
Home insurance is strictly based on Replacement Cost Value (RCV). This is the exact mathematical cost of hiring contractors to clear the debris and rebuild the physical structure of your house from the foundation up, using modern materials and current labor rates.
In 2026, due to localized inflation on lumber, copper, and skilled labor, your Rebuild Cost is often significantly higher than your Market Value. If you buy a house for $350,000, but it costs $450,000 to rebuild it after a total loss, and you only insured it for $350,000, you are underinsured by $100,000. You will have to pay that difference out of pocket to finish construction.
The Anatomy of a Standard HO-3 Policy
In the United States, the most common type of homeowners insurance is the HO-3 Special Form policy. It is built on six distinct pillars of coverage, labeled Coverage A through Coverage F.
Coverage A: Dwelling (The Structure)
This is the core of your policy. It covers the physical structure of your home and anything permanently attached to it. This includes the roof, foundation, load-bearing walls, built-in cabinetry, central HVAC systems, and attached garages.
- The Rule: You must insure Coverage A for 100% of the home’s calculated Replacement Cost.
Coverage B: Other Structures
This covers detached physical structures on your property. Fences, freestanding tool sheds, detached garages, gazebos, and in-ground swimming pools fall under Coverage B.
- The Rule: This limit is automatically set at 10% of your Coverage A limit. If your home is insured for $400,000, you have $40,000 in coverage for your fence and shed.
Coverage C: Personal Property (Your Belongings)
If you took your house, turned it upside down, and shook it, everything that falls out is personal property. Furniture, clothing, electronics, kitchenware, and sporting equipment.
- The Rule: Coverage C is usually set at 50% to 70% of your Coverage A limit.
The ACV vs. RCV Reality Check: You must check your policy to see how your personal property is valued. If you have Actual Cash Value (ACV), the insurer deducts depreciation. If a fire destroys your 10-year-old leather couch, they will write you a check for $200 (its garage sale value). You cannot buy a new couch for $200. You must upgrade your policy to Replacement Cost Value (RCV) for your personal property. RCV pays exactly what it costs to buy a brand new equivalent couch today.
Coverage D: Loss of Use (Additional Living Expenses)
If a kitchen fire renders your home legally uninhabitable while contractors rebuild it, you still have to pay your mortgage. You also have to pay for a hotel. Coverage D (or ALE) pays for your hotel, restaurant meals, pet boarding, and extra commuting costs while you are displaced.
- The Rule: Generally capped at 20% of your Coverage A limit, or limited to a specific timeframe (e.g., 12 to 24 months).
Coverage E: Personal Liability (The Lawsuit Shield)
This is the most undervalued protection you own. If the mail carrier slips on your icy driveway and fractures their spine, they will sue you. If your dog bites a neighbor’s child, they will sue you. Coverage E pays for your legal defense team and any court judgments against you, up to the policy limit.
- The Rule: Standard policies default to $100,000 in liability. That is dangerously low in 2026. A single dog bite claim can exceed $60,000. Upgrade this limit to $300,000 or $500,000 immediately. It costs roughly $20 a year.
Coverage F: Medical Payments to Others
This is “goodwill” coverage. It pays minor medical bills (usually between $1,000 and $5,000) for guests injured on your property, regardless of who is at fault. It is designed to quickly pay for a few stitches or an urgent care visit to prevent a minor accident from escalating into a massive Coverage E liability lawsuit.
Table 1: The Anatomy of an HO-3 Policy
| Coverage Section | What It Protects | Standard Default Limit | Broker Recommended Limit |
| A: Dwelling | The physical house structure. | Varies | 100% of accurate Rebuild Cost. |
| B: Other Structures | Fences, detached garages. | 10% of Coverage A | 10% (Unless you have a massive custom barn/pool). |
| C: Personal Property | Furniture, electronics, clothes. | 50% of Coverage A | 50% to 70% (Must be Replacement Cost, not ACV). |
| D: Loss of Use | Hotel & food if displaced. | 20% of Coverage A | 20% (Ensure it covers at least 12 months). |
| E: Personal Liability | Lawsuits for injuries/damage. | $100,000 | $300,000 to $500,000 minimum. |
| F: Medical Payments | Minor guest injuries. | $1,000 | $5,000. |
Exactly What Does Home Insurance Cover? (The 16 Named Perils)
Under a standard HO-3 policy, your personal property (Coverage C) is only protected against specific, named disasters. These are known in the industry as the 16 Named Perils. If a disaster is not on this list, you get zero dollars for your ruined belongings.
- Fire or Lightning: The most devastating and common major claims.
- Windstorm or Hail: Roof damage, shattered windows.
- Explosion: Gas leaks resulting in structural damage.
- Riot or Civil Commotion: Property destruction during unrest.
- Damage caused by Aircraft: Debris falling from the sky.
- Damage caused by Vehicles: A drunk driver crashing through your living room wall.
- Smoke: Sudden, accidental smoke damage (not from an ongoing industrial source nearby).
- Vandalism or Malicious Mischief: Intentional destruction by third parties.
- Theft: Break-ins stealing your electronics or jewelry.
- Volcanic Eruption: Airborne ash and lava flow.
- Falling Objects: A dead oak tree crushing your roof.
- Weight of Ice, Snow, or Sleet: Roof collapse from winter storms.
- Accidental Discharge or Overflow of Water: A suddenly burst pipe.
- Sudden Tearing Apart, Cracking, or Bulging: Hot water heater explosions.
- Freezing: Burst pipes due to extreme cold (provided you left the heat on).
- Sudden Electrical Damage: Power surges destroying appliances.
The “Sudden and Accidental” Rule: Look closely at those perils. Insurers demand that damage be sudden and accidental. If a pipe violently bursts at 2:00 AM and floods your kitchen, the damage is covered. If a pipe has been slowly dripping behind a wall for four months, rotting the drywall and spawning black mold, the claim will be denied. Slow leaks are classified as a failure to maintain the property.
The Unforgiving Exclusions (What is NEVER Covered)
Understanding your exclusions is far more important than understanding your coverages. An adjuster will look for these explicit exclusions the moment they step onto your property.
1. Flooding
In insurance law, water damage and flood damage are two entirely different things. A burst pipe is water damage. Flooding is defined as a general and temporary condition of partial or complete inundation of normally dry land area from the overflow of inland or tidal waters, or the rapid accumulation of surface waters.
- The Reality: Standard home insurance NEVER covers floods. If a hurricane pushes a storm surge into your living room, or a nearby river overtops its banks, your HO-3 policy pays absolutely nothing. You must buy a separate policy from the National Flood Insurance Program (NFIP) or a private flood carrier.
2. Earth Movement
Earthquakes, landslides, mudflows, and sinkholes are strictly excluded. If an earthquake registers 7.0 and shakes your house off its foundation, standard home insurance offers zero protection. Residents in high-risk zones (like California) must purchase dedicated earthquake policies with massive, separate deductibles (often 10% to 15% of the home’s value).
3. Wear and Tear (The Maintenance Rule)
Insurance is designed to cover catastrophic anomalies. It does not cover the inevitable degradation of building materials. If your asphalt shingle roof is 25 years old and starts leaking during a standard rainstorm, the insurance company will deny the claim. They will state the roof simply reached the end of its natural lifespan.
4. Pest Infestations
Termites, mice, rats, bedbugs, and raccoons cause billions of dollars in property damage annually. None of it is covered. Insurers classify pest control as routine home maintenance. If termites hollow out a load-bearing beam and your floor collapses, the repair bill is entirely your responsibility.
5. Neglect and Intentional Acts
If you leave town in January, turn the furnace completely off to save money, and your pipes freeze and shatter, the claim is denied. You neglected to maintain heat in the dwelling. Similarly, if you intentionally set fire to your own home to collect a payout, you will receive nothing and be prosecuted for insurance fraud.
The Complex Water Damage Matrix
Water is the number one cause of property damage in the United States. It is also the number one source of denied claims because consumers do not understand the source distinctions. Use this matrix to understand exactly how adjusters classify water.
Table 2: The Water Damage Matrix
| Source of Water | Example Scenario | Is It Covered by a Standard HO-3? |
| Top-Down (Sudden) | A massive tree branch punches a hole in the roof during a storm, allowing rain to soak the living room. | Yes. Covered under Windstorm peril. |
| Internal (Sudden) | The braided steel hose on your washing machine ruptures, flooding the laundry room. | Yes. Covered under Sudden Discharge. (Note: They pay to fix the room, not to buy a new washing machine). |
| Internal (Gradual) | The P-trap under the kitchen sink drips silently for 6 months, rotting the subfloor. | No. Excluded as long-term seepage and maintenance failure. |
| Rising Water (External) | Heavy spring rains cause a nearby creek to overflow, sending two inches of water into the first floor. | No. Strictly excluded as a Flood. Requires a separate NFIP policy. |
| Bottom-Up (Sewers) | The city sewer line gets clogged, forcing raw sewage to back up through your basement drains. | No. Excluded by default. Requires a specific “Water Backup” endorsement to trigger coverage. |
Essential Endorsements (Riders You Actually Need)
An HO-3 policy is a blank canvas. To achieve true financial security, you must bolt on specific endorsements (also called riders) to close the massive exclusion gaps.
Water Backup and Sump Overflow
As highlighted in the matrix above, if a municipal sewer backs up into your home, standard policies deny the claim. A Water Backup endorsement overrides this exclusion. It usually costs less than $50 a year and provides $10,000 to $25,000 in coverage to rip out sewage-soaked drywall, sanitize the framing, and replace the flooring. Never buy a policy without this rider.
Ordinance or Law Coverage
If your home was built in 1980 and a fire destroys half of it today, you cannot just rebuild it the way it was. You must rebuild it to 2026 local building codes. This might mean rewiring the entire house, updating HVAC ventilation, or adding specialized roof trusses. Standard insurance only pays to put the house back exactly as it was. The city will force you to pay for the modern upgrades. Ordinance or Law coverage pays that gap, covering the legal cost of bringing an older home up to modern municipal code.
Scheduled Personal Property
Coverage C protects your belongings, but it enforces strict “sub-limits” for high-theft items. A standard policy will only pay a maximum of $1,500 total for stolen jewelry, firearms, or cash, regardless of your overall limit. If a burglar steals your $12,000 engagement ring, the insurer hands you a check for $1,500. To protect valuables, you must “schedule” them. This involves giving the insurer an appraisal for the specific ring and paying a few extra dollars a month to insure it for its full appraised value with no deductible.
HO-3 vs. HO-5: Choosing the Right Policy Form
While the HO-3 is the standard, high-net-worth individuals or those with significant assets should ask their broker about an HO-5 Comprehensive Form.
An HO-3 operates on an “Open Peril” basis for the structure of the house (Coverage A), meaning the house is covered against everything except what is explicitly excluded. However, it operates on a “Named Peril” basis for your personal belongings (Coverage C), meaning your stuff is only covered if the disaster is on the 16 Perils list.
An HO-5 operates on an “Open Peril” basis for both the house and your belongings.
The Burden of Proof:
Under an HO-3, if you claim a painting was ruined, the burden of proof is on you to prove that one of the 16 named perils caused the damage. Under an HO-5, the burden of proof shifts to the insurance company; they have to pay the claim unless they can prove the damage was caused by a specific exclusion. An HO-5 provides vastly superior protection for high-value personal property.
Review Your Coverage Annually
Your risk profile is not static. If you renovated your kitchen this year, adding $40,000 in custom cabinets and stone countertops, your current Replacement Cost limit is now dangerously low. If you bought a trampoline for your kids, your liability risk just skyrocketed.
Do not let your home insurance auto-renew in the background. Sit down with a licensed property and casualty broker every 12 months. Review your Coverage A limits against current local construction costs, verify your personal property is valued at Replacement Cost, and ensure you have bolted on the Water Backup endorsement. Understanding what your policy covers before a disaster is the only way to guarantee your home remains an asset rather than a financial liability.